


The credit score you need to qualify for a student loan depends on whether you’re applying for a federal or private loan. Most federal student loans don’t require a credit check, while private lenders typically look for a FICO score of at least 670. Generally, the higher your credit score, the better your chances of qualifying for a lower interest rate.
Here’s how your credit score affects student loan approval and what else lenders consider.
Compare private student loan rates
What you should know: Your credit score isn't the only factor lenders consider. If you have a steady income and relatively little debt, you may still qualify for a private student loan with less-than-perfect credit. Lenders want to see that you can comfortably afford your monthly loan payments.
What credit score do you need for federal student loans?
Most federal student loans, including Direct Subsidized and Unsubsidized Loans, don't require a credit check or minimum credit score. You can qualify even if you have bad credit or no credit history.
Parent PLUS loans are the exception. While there's no minimum credit score, you must undergo a credit check to determine whether you have an adverse credit history.
The Department of Education considers your credit history adverse if you have:
- Accounts totaling $2,085 or more that are at least 90 days delinquent, in collections, or charged off.
- A bankruptcy discharge, foreclosure, repossession, tax lien, wage garnishment, or certain other negative credit events within the past 5 years.
You may still qualify for a PLUS Loan with adverse credit by applying with an endorser who doesn't have adverse credit or documenting extenuating circumstances. You'll also need to complete PLUS credit counseling.
Learn More: Direct PLUS Loans: A Guide for Parents and Graduate Students
What credit score do you need for private student loans?
Most private student loan lenders require a credit score in the mid-600s to qualify, though requirements vary by lender. Some lenders don't disclose their minimum credit score requirements.
To get an idea of what credit score you might need, the table below shows minimum credit score requirements for private student loan lenders on Credible:
Source: Credible
How does your credit score affect your student loan interest rate?
Your credit score determines the interest rate you qualify for on a private student loan. Generally, the higher your score, the lower your interest rate is likely to be. A lower rate means smaller monthly payments and less interest paid over the life of the loan.
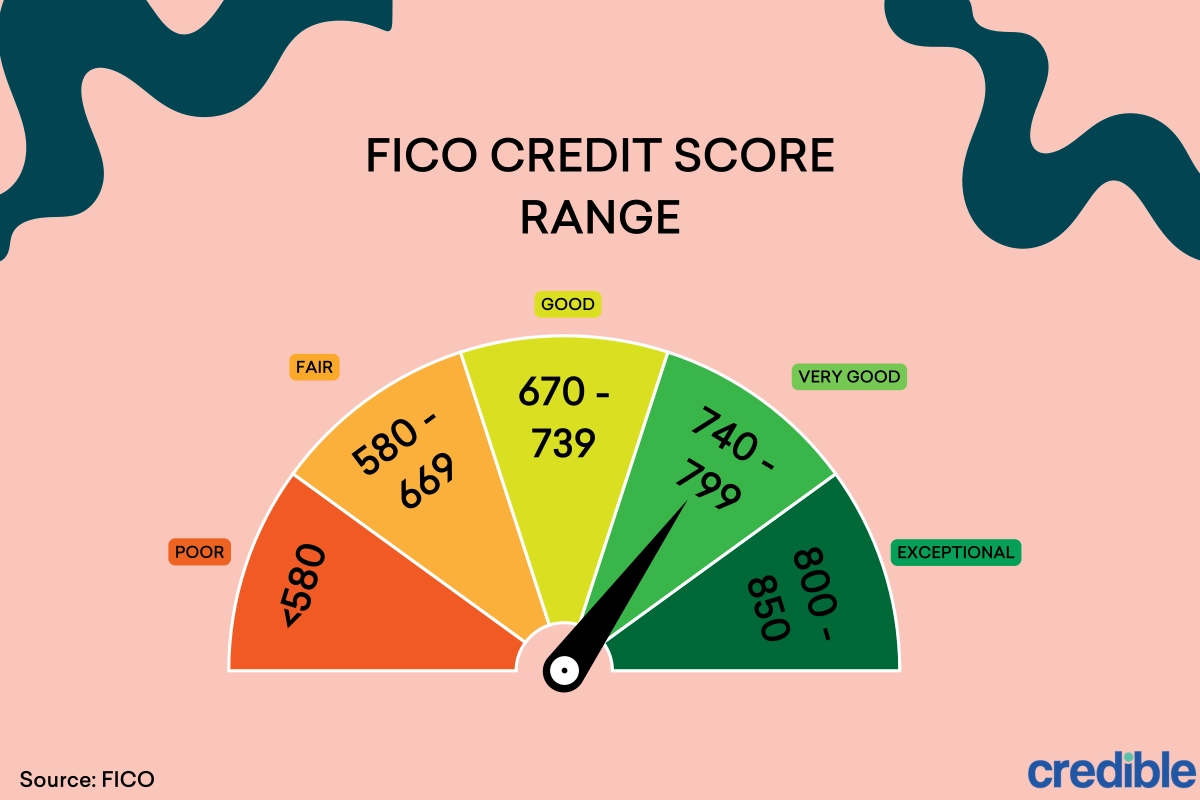
Many private lenders use FICO credit scores to evaluate applicants. FICO scores range from 300 to 850 and fall into five categories:
This chart shows average prequalified interest rates by credit score for borrowers who used Credible to compare private student loans:
What credit score does my cosigner need?
Most private student loan lenders prefer cosigners with good to excellent credit, typically a FICO score of at least 670. Your cosigner needs sufficient income and a low debt-to-income ratio (DTI) to show they can afford the loan payments if you can't make them.
A cosigner may help lower your rate, but only if their credit is strong. If it isn’t, you could still face a relatively high interest rate. The average rate for Credible borrowers with a cosigner scoring below 680 was 11.93% in September 2026.
How to check your credit score
You’re entitled to a free copy of your credit report from each of the three credit-reporting bureaus — Equifax, Experian, and TransUnion — once per year.
You can use Credible's free credit monitoring tool to request these reports and review your credit history easily. If you find any errors in your credit reports, dispute them with the appropriate credit bureaus to potentially boost your score.
However, your credit reports generally don’t include your credit score. You can check your credit score for free through your bank, credit card issuer, or a free online service. You can also request your score directly from the credit bureaus.

Tip
It’s a good idea to monitor your credit score regularly. This way, you can keep an eye on any changes and look out for errors or fraud.
How to raise your credit score
To get the most competitive rates or increase your chances of being approved for a student loan without a cosigner, here are some tips on how to raise your credit score:
- Get a secured credit card and keep up with monthly payments.
- Monitor your credit history and dispute any mistakes.
- Ask to raise your credit limit if you have an existing credit card.
- Become an authorized user on someone else’s credit card.
- Pay down existing loans on time.
FAQ
Do you need credit for student loans?
Open
Do you need good credit for student loans?
Open
Do federal student loans affect your credit score?
Open
What credit score do you need for a private student loan?
Open
Can you get a private student loan without a credit history?
Open
Sarah Li-Cain contributed to the reporting for this article.


