


Student loans for bad credit can be challenging to find, but there are still ways to borrow money for college if you have a low credit score from missed payments or collections, or limited credit history. Federal student loans have no credit score requirements, making them a popular option with bad-credit borrowers.
If federal student loans aren't enough to cover the cost of your education, you can turn to private student loans to bridge the gap. While private loans have minimum credit score requirements, you have other options, such as adding a cosigner to your application, to improve your chances of qualifying.
Here's what you need to know about taking out student loans with bad credit.
Compare private student loan rates
Can you get a student loan with bad credit?
You can get a student loan with bad credit, but your options depend entirely on whether you apply for federal or private student loans.
Credit scores affect your ability to secure funding in two main ways:
1. Federal student loans (best for bad credit)
For most federal student loans, your credit score doesn’t matter.
- No credit check: The government doesn’t check your credit history for standard undergraduate Direct Subsidized Loans or Direct Unsubsidized Loans for undergraduate and graduate students.
- Equal rates: All borrowers with the same loan type get the same fixed rate, regardless of credit. For the 2026-27 school year, that's 6.52% for undergraduate loans, 8.07% for graduate loans, and 9.07% for PLUS loans.
2. Private student loans (most difficult for bad credit)
Private lenders view a low credit score as a major red flag.
- Credit requirements: To qualify without a cosigner, many lenders require “good” credit, which is a FICO score of at least 670.
- Higher costs: If you are approved with bad credit, lenders will charge you significantly higher interest rates, costing you more over the life of the loan.
- Fewer options: A low score limits your choice of repayment terms and lender perks.

Keep in mind
Most federal student loans don't have a credit requirement. Private lenders set their own minimum credit requirements, and many don't publish them. Prequalifying with several lenders is often the best way to find out whether you qualify.
What’s considered bad credit for student loans?
A bad credit score is a rating that signals to student loan lenders that you pose a higher risk as a borrower. The specific number that defines a “bad” score depends on the credit scoring model being used:
- FICO score: Anything below 580 is classified as “poor.”
- VantageScore 3.0: Anything below 600 is classified as “poor” or “very poor.”
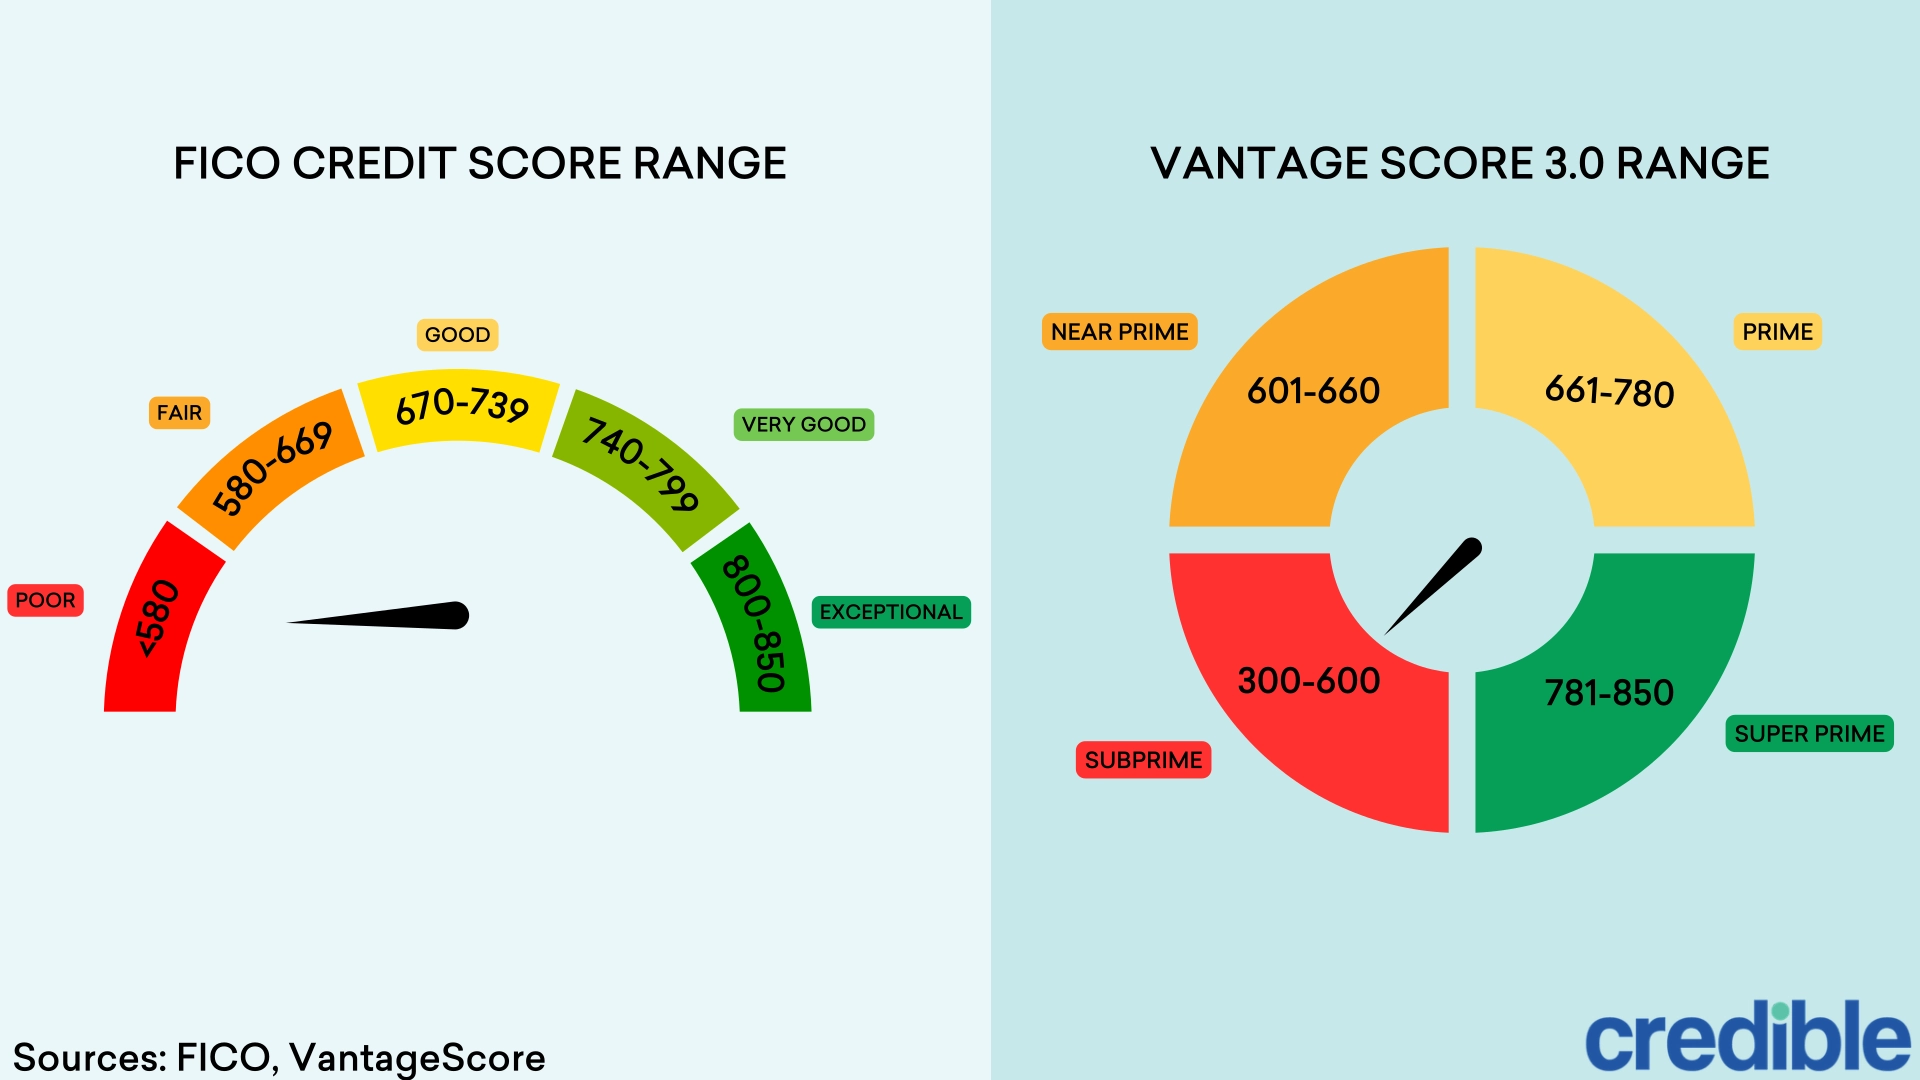
How a bad credit score affects borrowing
- High risk: A bad credit score suggests a history of missed payments, high debt utilization, or poor credit management.
- Higher interest rates: To compensate for the risk, lenders charge bad-credit borrowers significantly higher interest rates for student loans.
- Loan denials: A bad score can make it difficult to get approved for student loans or other debt, such as mortgages and auto loans.
Federal student loans for bad credit
If you have a low credit score, consider federal student loans first. A credit check generally isn’t part of the federal requirements for student loans, which is why it usually makes sense to use federal loans before private loans. Borrow only what you need, since Direct Unsubsidized Loans start accruing interest while you're in school.
Direct Subsidized and Unsubsidized Loans, the most common types of federal student loans, are available to students regardless of their credit history, provided the borrower hasn’t defaulted on a federal loan in the past.
Parent PLUS loans require a credit check, but not a minimum credit score. The Department of Education looks for an adverse credit history, like recent bankruptcy, foreclosure, or repossession. If you have one, you’ll need an endorser (the equivalent of a cosigner for private student loans) who has good credit or documentation showing that your adverse credit was due to extenuating circumstances.
Submit a Free Application for Federal Student Aid (FAFSA) to see if you qualify for Direct Loans despite having bad credit.
Private student loans for bad credit
Some private student loans are specifically designed for students with no or low credit. These loans are similar to traditional private student loans but may offer lower borrowing amounts, higher interest rates, or shorter repayment terms.
A few lenders also offer loans that don’t consider credit but instead look at other criteria. For example, Ascent offers an outcomes-based loan for college juniors and seniors who can't qualify on their own credit and don't have a cosigner. Instead of relying on credit, Ascent may consider factors like your school, major, GPA, graduation date, and cost of attendance. You'll need a GPA of at least 3.0, and you can borrow up to $20,000 a year.
Other private lenders require a FICO score in the mid-600s, including Citizens, Abe, and Custom Choice.
Student loan options for parents with bad credit
If you're a parent with bad credit, you have two main student loan options:
Parent PLUS loans
Parent PLUS loans have historically allowed you to borrow up to your child’s school-certified cost of attendance, minus other financial aid received. A credit inquiry that checks for an adverse credit history — such as a recent bankruptcy or foreclosure — is required to qualify, but there’s no minimum credit score needed.
As of the 2026-27 school year, parent PLUS loans are capped at $20,000 per year per dependent student and $65,000 total per student. Existing borrowers may be able to continue using parent PLUS loans under the full cost-of-attendance rules for up to three more academic years, or until the student finishes the program, whichever comes first.

Good to know
If you’re a parent and denied a parent PLUS loan, the student you’re borrowing for may qualify for higher Direct Unsubsidized Loan limits, depending on their year in school and dependency.
Private parent loans
Some private lenders offer parent loans, but they typically require a minimum credit score and strong income. If you have bad credit, qualifying may be more difficult — though a steady income or other financial strengths could improve your chances with certain lenders.
Current private student loan interest rates for parents range from 2.84% to 17.99% for fixed rates and 3.89% to 17.99% for variable-rate loans through Credible. Applying with a cosigner can also improve your eligibility and help you qualify for lower rates. In the last 12 months, borrowers who took out private student loans with a cosigner through Credible received, on average, rates that were nearly 1.5 percentage points lower than those who applied without one.
Use a cosigner to get a student loan with bad credit
Most private student lenders let you apply with a cosigner, who is an individual who meets the lender’s income and credit criteria and agrees to be equally responsible for the loan. If you miss payments, it can hurt your cosigner's credit, and the lender can collect from them.
By leveraging a cosigner’s creditworthiness, you have a better chance of getting approved and securing a better interest rate and terms. Since this is a major responsibility, a cosigner is typically someone with a close relationship to the primary borrower (for example, the student’s parent, spouse, grandparent, or older sibling).
Some lenders offer a cosigner release feature in their loan agreements. If your credit improves later on, this feature lets you remove your cosigner’s obligation from the debt. But you’ll need to meet the lender’s release requirements first.
How to improve your credit before applying for a student loan
If you still have several years of school ahead before graduating, it might be a good idea to start improving your credit today. This could work in your favor the next time you need a loan.
Your credit is impacted by multiple factors, but these are some of the most immediate and effective ways to improve it:
- Repay debt on time: A large part of your FICO score (35%) is calculated based on your payment history, which includes whether you've made minimum monthly payments on time on your outstanding debts. Make sure you're paying off your student loans and other debts on time and for the full amount due.
- Lower unpaid debt balances: Your debt, such as credit card balances, can affect your student loan approval. If you lean on your credit too heavily, lenders might perceive you as a high-risk borrower who's financially overextended. Before applying for a student loan with bad credit, consider paying down your other revolving debt.
- Avoid opening new accounts: When you apply for new lines of credit, lenders conduct a hard credit check, which temporarily lowers your credit score. Applying for new credit cards or other installment loans, in addition to your student loan, within a short period could drag your score down when you're trying to improve it.
- Review your credit report: Sometimes your credit score can be dragged down by a data reporting error. For example, your score could be lowered if the report includes a defaulted debt that isn't actually yours. Request a free copy of your credit report from AnnualCreditReport.com. You can check your reports for free every week. If you find a mistake, dispute it with each bureau reporting it: Experian, Equifax, or TransUnion.
- Become an authorized user: Asking a responsible loved one to add you as an authorized user on their credit card can help build and improve your credit, as their history of on-time payments is added to your credit report.
Editor insight: “You may start to see small credit score improvements within 30 to 45 days of making on-time payments and lowering debt balances, but it can take several months to see a meaningful change. If you're borrowing for the fall semester, I recommend working on your credit for a few months before applying for a student loan.”
— Renee Fleck, Student Loans Editor, Credible
Other ways to pay for school with bad credit
Federal and private student loans are just one type of financial aid you can turn to. Alternative aid options to look into include:
- Grants: This kind of aid typically doesn't have to be repaid. You can find college grants at the federal and state levels, as well as through your school, private companies, and nonprofits.
- Scholarships: This is another form of gift aid that awards students based on financial need or merit, and deadlines run year-round, so it's worth checking often. You can get a scholarship based on your field of study, academic achievement, community involvement, interests, or skills.
- Income-share agreements (ISAs): ISAs are a type of alternative loan that offers lump-sum financing up front for school, which you'll repay using a fixed percentage of your future salary for a certain number of years.
FAQ
What are the 2026 changes to federal student loans?
Open
Can I get student loans for bad credit?
Open
What is considered bad credit when it comes to student loans?
Open
Are federal or private student loans better if I have bad credit?
Open
Which is the best private student loan lender for bad credit?
Open
Do I need a cosigner to get a student loan with bad credit?
Open
What credit score do you need for a student loan?
Open
Will applying for a bad-credit student loan affect my credit?
Open
How do I qualify for student loans with bad credit?
Open
Can you be denied a student loan because of bad credit?
Open
How do you apply for a student loan with bad credit?
Open


